Venmo

- 340.13K Reviews
- 4.1
- Downloads
- 50,000,000+
 Analysis by Appgk
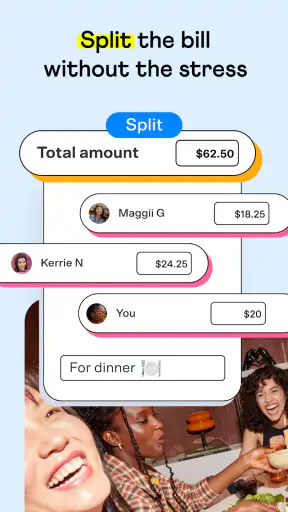
I find a shared meal is where Venmo makes the most immediate sense. One person pays the restaurant bill, then everyone else can send their share without passing cash around or trying to remember who owes what the next day. The same pattern works for household supplies, a group gift, or a shared ride: the person who pays requests the right amounts, and each person can handle their part on their own phone. That convenience is most useful when everyone involved already has an account and is comfortable using a payment app.
For a household, I’d treat it as a way for separate adults to settle expenses, not as a shared family wallet. Each person should use their own account and keep their sign-in details private. That makes it easier to see who sent a payment and avoids the muddle of several people acting through one profile. I also wouldn’t leave a signed-in phone where other household members can casually make payments; a device may be shared, but money decisions should remain tied to the account holder.
Setting boundaries before money moves
It helps to agree on a simple routine before relying on the app for recurring household costs. Decide who pays a bill, when the others should send their shares, and what the payment note should say. A clear note such as “utilities” or “groceries” is more useful later than an inside joke, especially when several payments happen close together. Venmo’s social touches can make transfers feel casual, but a payment record still needs to make sense to the people involved.
I’d also check privacy choices before sending the first household payment. Venmo lets you choose who can see a transaction, and I’d make private the default for routine rent contributions, shared shopping, or reimbursements. That keeps ordinary financial details from becoming part of a social display. If someone is using a device that other people can access, a PIN or biometrics can add a practical barrier, though it doesn’t replace keeping account access personal.
One useful habit is to settle a request promptly and then check that the amount and recipient are right before confirming. That small pause matters when two people have similar names or when you’re paying while distracted. I’d avoid treating an emoji or a quick message as a substitute for checking the actual payment details. A few seconds of care are easier than sorting out a mistaken transfer later.
Keeping a household coordinated
Venmo is strongest when the arrangement is simple: one person pays, the others reimburse them, and everyone can identify what the payment covered. It is less suited to managing a complicated household budget. It doesn’t replace a shared spreadsheet, a bill calendar, or a conversation about who is responsible for which expense. I’d use it to move money after the group agrees on the numbers, not to decide those numbers.
For example, if one roommate buys cleaning supplies and another covers a shared meal later that week, each can request or send the relevant amount as the expense happens. That is easier to follow than letting small debts accumulate until the end of the month. The trade-off is that frequent little transfers can clutter the activity history, so consistent notes and a regular settlement day may suit a busier household better.
News Picks to Read Next
View All News
When comparing it with a bank transfer, the appeal here is the social, lightweight flow for paying people you know. A bank’s own payment tools may be a better fit for someone who wants all activity inside their existing banking setup, while cash can still be simpler for an occasional exchange with someone who doesn’t use Venmo. I wouldn’t choose a peer-to-peer app as the household’s only record of shared spending; the group should keep whatever budget or bill records it needs separately.
Age, trust, and who should use it
The app is rated for Everyone, but that label is not a recommendation for a child to manage household money. I’d keep account use with the adult who owns the account and make sure younger family members understand that sending money is a real financial action, not just another social interaction. The playful feed may soften the feel of a transaction, so clear boundaries matter more than the app’s casual tone.
Best Parts of Venmo
Things to Keep in Mind About Venmo
Venmo is a good fit for adults who regularly split costs with friends, roommates, or relatives and want a quick way to settle up. It’s less compelling if your household rarely reimburses one another, if everyone prefers cash, or if you want a dedicated system for tracking bills and balances. It also won’t solve disagreements about how much each person owes: those still need a direct conversation.
Venmo is a finance app from developer Venmo. It is free, has an average rating of 4.1 from around 871,000 ratings, and has passed 50 million installs. It first appeared on May 17, 2010; the current version is 10.78.1, and it requires Android 8.0 or later. Its age rating is Everyone, a broad store label that should not be confused with household account supervision.
Getting Started with Venmo
First off, setting up Venmo is a breeze. All you need is to download the app, which is available for both Android and iOS, sign up with your email or Facebook, and link your bank account or card. Boom, you’re ready to go! The interface is super intuitive, making it easy even for the less tech-savvy among us.
One cool thing I noticed right away is the social feed. Think of it like a mix between your typical payment app and a social media platform. You can see who’s paying who and for what, with fun emojis and comments sprinkled in. It’s a quirky touch that adds a bit of personality to the otherwise mundane task of money transfers.
Features That Stand Out
The app is not just about paying and requesting money. Venmo offers a few other features that really stand out. For one, you can use Venmo to pay at select retailers both online and in-store, which is pretty handy. Plus, if you’re into cryptocurrencies, Venmo lets you buy, sell, and hold them directly in the app.
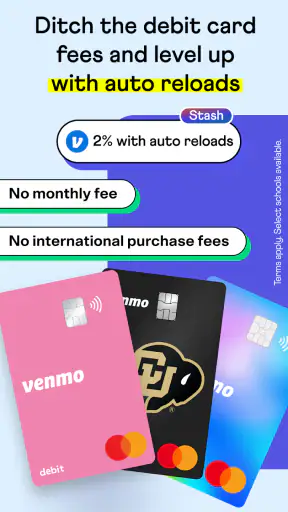
Another feature that caught my eye is the Venmo card. You can order a physical card linked to your account, which you can use anywhere Mastercard is accepted. It’s like having your Venmo balance available at your fingertips, literally!
Screenshots
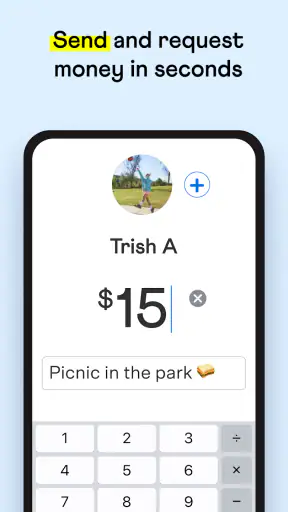
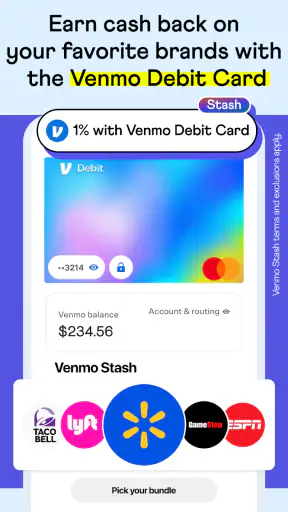
Privacy and Security
Now, let’s talk about something that’s on everyone’s mind these days: security. Venmo takes this seriously. You can set up a PIN or use biometrics to add an extra layer of protection. Plus, you have control over who sees your transactions. You can choose between public, friends-only, or private settings for each transaction, which is a nice touch.
Still, I’d recommend keeping your transactions as private as possible. The social aspect is fun, but it’s important to remember you’re dealing with real money here.
Overall Experience
Using Venmo has been a smooth experience overall. The app is responsive, and the transactions are swift. It’s particularly useful when you’re out with a group and need to split costs quickly. No more awkward "I’ll pay you back later" moments. You can settle things instantly.
Sure, there are some fees involved if you’re using a credit card or opting for instant transfers, but they’re pretty standard across payment apps. Just something to keep in mind if you’re planning on using those features frequently.
In conclusion, Venmo makes managing payments with friends and family straightforward and even a bit fun. It’s not perfect, but it’s pretty darn close. So, if you haven’t already, give it a whirl and see how it fits into your financial life. Trust me, you won’t be disappointed.
Venmo FAQ
What are the main features of Venmo?
Venmo is a mobile payment service that allows users to transfer money to others quickly and securely. Key features include the ability to pay and request money, split bills, and make purchases online or in-store using a Venmo card. Users can also connect their bank accounts or credit cards for seamless transactions. Additionally, Venmo offers a social feed to share and comment on payments, adding a social aspect to financial transactions.
Is Venmo safe to use for money transfers?
Yes, Venmo uses encryption and security measures to protect user information and transactions. It provides multi-factor authentication and allows users to set up PIN codes for additional security. However, like any financial service, users should remain vigilant, avoid sharing personal information, and ensure they only transact with trusted individuals or businesses to minimize risks.
Are there any fees associated with using Venmo?
Venmo is free to use for transferring money between friends and family if linked to a bank account or debit card. However, there is a 3% fee for using a credit card to send money. Venmo also charges fees for instant transfers to bank accounts and certain business transactions. It's important to review the fee structure on Venmo's website for specific details.
Can I use Venmo internationally?
Venmo is currently only available for users within the United States. Users must have a U.S. bank account or debit card to use the service. While you can access Venmo from abroad, transactions can only be made with other U.S.-based accounts, and foreign transactions are not supported at this time.
How does Venmo's social aspect work?
Venmo incorporates a social feed where users can share their transactions with friends. This feature lets users add notes, emojis, and comments to payments. While it adds a fun, interactive element, users can adjust privacy settings to control who can see their transactions, ensuring sensitive financial information remains private.